
Benefits of Owning Physical Gold Bullion in 2026
Table of Contents
- What Physical Gold Bullion Actually Is
- Physical Gold vs Gold ETFs: What You Own Matters
- Gold as an Inflation Hedge and Store of Value
- Portfolio Diversification and Liquidity Benefits
- Gold Bullion Tax Rules: What the IRS Requires
- How to Store Physical Gold Bullion Safely
- Authentication, Exit Strategy, and Common Mistakes
- Frequently Asked Questions
Last Updated: September 14, 2026
What Physical Gold Bullion Actually Is
Physical gold bullion is gold in its purest tradable form: bars, rounds, or sovereign coins valued by metal content and purity rather than collector appeal. The core benefit: you hold a tangible asset outright, outside the banking system, with no intermediary between you and the metal.
Douglas Ginter, author of GOLD: The Most Precious of Metals, makes one point repeatedly: gold’s case rests on what it is, not on a story someone is selling you.
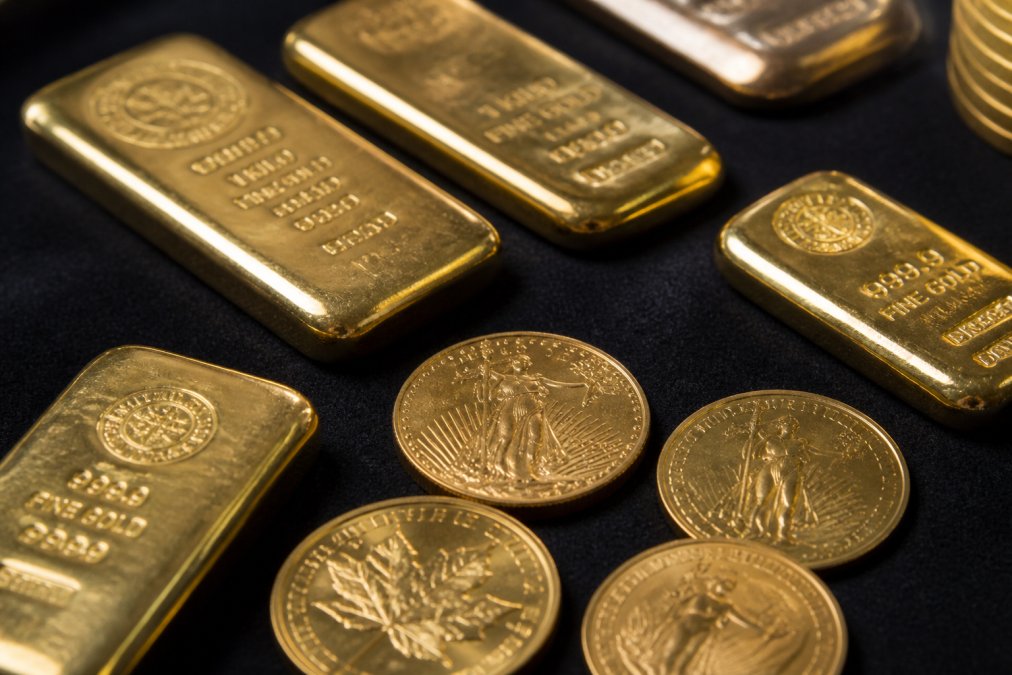
Bullion is measured in troy ounces and stamped with its purity, often .999 or higher for modern bars and coins, letting a dealer verify it in seconds rather than sending it off for assay.
Physical Gold vs Gold ETFs: What You Own Matters
An ETF gives you price exposure. Physical gold bullion gives you the metal. That distinction decides everything that follows.
When you buy gold ETF shares, you own a security issued by a fund. The fund may hold metal, but you hold paper: you cannot take delivery, and your position depends on the fund’s structure holding up.
| Feature | Physical Gold Bullion | Gold ETF |
|---|---|---|
| What you own | The metal itself | Fund shares |
| Counterparty risk | None | Fund and custodian |
| Storage | Your responsibility | Built into the fund |
| Liquidity | Dealer or private sale | Sell during market hours |
| Tax treatment | Collectibles rate on gains | Collectibles rate on gains |
Counterparty Risk and Direct Ownership
Counterparty risk is the chance the other side of your position fails to perform. With direct ownership of bullion, that risk largely disappears, no fund manager, custodian, or broker stands between you and the asset. During financial stress, paper claims on metal and the metal itself are not the same thing.
The core benefit of physical gold bullion is not the price chart. It is that ownership is direct, with no intermediary whose failure becomes your problem.
Gold as an Inflation Hedge and Store of Value
Gold has served as a store of value for centuries, which is why many investors treat it as an inflation hedge. When fiat currency loses purchasing power, gold’s price in those terms often rises over long periods.
A common mistake is expecting that relationship to hold month to month. It does not. Gold can lag inflation for years, then move sharply. World Gold Council research on gold’s long-term role frames it as a strategic holding, not a timing trade.
How Gold Performs During Economic Crisis
During economic crisis and geopolitical instability, gold tends to attract demand as a safe haven. It does not rise in every crisis, but its value never rests on a single issuer’s creditworthiness, for wealth preservation, that independence is the point.
Portfolio Diversification and Liquidity Benefits
Adding gold to a portfolio is a portfolio diversification move because gold often moves independently of stocks and bonds; a modest asset allocation can reduce overall swings. Liquidity is the other half: gold is among the most liquid precious metals, sellable to dealers, coin shops, or private buyers, with the spot price as a transparent benchmark.
- Global market: gold trades continuously worldwide
- Recognized form: standard bars and sovereign coins are easy to price
- No lockup: you are not waiting on a fund’s redemption schedule
- Tangible asset: possession itself is the collateral
The catch is premiums and dealer markup: you buy above spot and sell below it. That spread is the real cost of owning physical metal, and why gold rewards patience over frequent trading.
Gold Bullion Tax Rules: What the IRS Requires
Gold is not tax-free. The IRS treats physical gold bullion as a collectible for capital gains purposes, so gains on metal held more than a year are taxed at the collectibles rate, higher than the long-term rate on most securities.
IRS guidance on capital gains and collectibles is the source to read directly, and IRS Topic 409 on capital gains and losses covers how gains and losses are reported. A few practical points:
- Keep every purchase receipt showing date, quantity, and price
- Sales of certain bullion may be reported by the dealer on Form 1099-B
- Short-term gains are taxed as ordinary income
- State rules vary, so check your own state’s treatment
Selling gold for cash and skipping the paperwork is a common mistake with real consequences. The IRS requires capital gains on bullion to be reported, and unreported sales can trigger penalties and interest.
How to Store Physical Gold Bullion Safely
Storage is where the romance of gold meets logistics. You need storage security and insurance, and the right answer depends less on preference than on the dollar value of what you hold, because every option has a different cost curve.
The Three Real Storage Options
Home storage. A bolted-down safe, a discreet location, and a homeowner’s policy or scheduled personal property rider are the basics. The trade-off: you become the security system. Most homeowner’s policies cap precious metals coverage at a low sub-limit unless you add a rider, so call your insurer first.
Bank safe deposit box. A box is inexpensive relative to value and physically off-site, but it is not insured by the bank, access is limited to branch hours, and contents are not segregated or audited. It also creates a paper trail tied to your identity, cutting against the privacy benefit of physical metal.
Click Here To Order Your Copy →
Professional vaulting. Depositories hold metal in either allocated (specific bars or coins titled to you, often with serial numbers) or unallocated (a pooled claim on a bulk holding) form. Allocated storage is the only form that preserves direct ownership; unallocated storage reintroduces the counterparty risk you bought physical metal to avoid, which is why segregated, audited storage costs more.
| Factor | Home Storage | Bank Safe Deposit Box | Professional Vaulting |
|---|---|---|---|
| Ongoing cost | Safe + rider premium | Annual box rental | Recurring fee on value |
| Access | Immediate | Branch hours only | Scheduled or by request |
| Security burden | On you | On the bank | On the facility |
| Insurance | Your policy or rider | Generally not covered | Facility or separate policy |
| Privacy | High | Low (identity on file) | Varies by provider |
| Ownership form | Direct possession | Direct possession | Allocated or unallocated |
The Cost-Benefit Math
Run the numbers as a percentage of holdings, not a dollar figure. A safe and rider policy are largely fixed costs, so their effective cost per dollar of metal falls as holdings grow; vaulting fees scale with value, so their effective cost stays roughly flat. For a small stack, a quality safe plus a scheduled rider is usually cheaper. For a large holding, the risk of a single-location loss dominates, which is when allocated vaulting earns its fee. There is no universal crossover point, but the shape of the curve is the same for everyone.
Unallocated storage is not the same product as allocated storage, even when both are marketed as ‘vaulted gold.’ If the depository can substitute bars or if you hold a pooled claim, you have counterparty exposure. Ask specifically whether your holdings are allocated, segregated, and audited, and get it in writing.
Insurance Mechanics
Insurance is the part most buyers get wrong. A standard homeowner’s or renter’s policy treats precious metals as a sub-limited category, so a total loss could leave most of your stack uncovered. Two fixes exist: a scheduled personal property rider listing specific items and appraised value, or a standalone precious metals policy from a specialty insurer. Riders are cheaper but usually require an appraisal and receipt trail; standalone policies cost more but cover broader perils and travel. Keep the documentation either way, receipts showing date, quantity, purity, and price are what an adjuster will ask for after a loss, and the same records you need at tax time.
Before you commit to any storage method, price the insurance first. A safe you cannot insure, or a vault whose coverage excludes the perils you actually fear, is not storage, it is a false sense of security.
The IRS Angle Most Guides Skip
Storage choice has a tax dimension. Physical metal held in a home safe or a bank box is in your direct possession, which keeps the reporting simple: you report the gain when you sell. Metal held through a depository can be structured in ways that create additional reporting or custodial arrangements, so read the depository agreement for how title and reporting are handled before you sign. The IRS treats physical gold bullion as a collectible for capital gains purposes, and IRS guidance on capital gains and collectibles is the source to read directly.
Authentication, Exit Strategy, and Common Mistakes
Most gold guides stop at ‘buy from a reputable dealer.’ That does not tell you how to verify what you bought, how to sell it without getting taken, or what the spread actually costs you.
How to Verify Bullion Before You Buy
Counterfeit bullion is real and good enough to fool a casual eye. The defenses are cheap and fast.
- Weight and dimensions. Every sovereign coin and standard bar has published specs for mass, diameter, and thickness. A one-ounce gold coin should weigh one troy ounce (about 31.1 grams) within a tight tolerance. A caliper and scale catch most fakes in under a minute.
- Ping test. Gold rings when struck. Counterfeits made of tungsten or base metal with gold plating sound dull. Free apps can measure the ring frequency against a known reference.
- Magnet test. Gold is not magnetic. A strong magnet should not attract a genuine coin. This test is necessary but not sufficient, some counterfeits use non-magnetic cores.
- Assay and XRF. For bars, an assay card from a recognized refiner is the baseline. For anything you cannot verify yourself, a local dealer or refiner can run an X-ray fluorescence (XRF) scan, which reads surface composition in seconds. A specific-gravity or ultrasonic test goes deeper and is worth it for large bars.
The most common counterfeit pattern is a tungsten core wrapped in real gold, which passes weight, magnet, and visual checks. On any bar you did not buy new in sealed packaging from a recognized refiner, insist on an XRF or ultrasonic test before you pay.
Your Exit Strategy: Where the Metal Actually Goes
Decide now where you would sell, because the answer determines what you should buy. Four channels differ in speed, price, and paperwork.
Local coin shop or dealer. Fast, no shipping risk, negotiable in person, but the dealer’s buy price is their wholesale number, below spot. The default channel for most small and mid-size sales.
Online bullion dealer buyback. Many dealers who sell to you also buy back, often closer to spot than a local shop, but you ship first, which means insurance, tracking, and a settlement window measured in days.
Private sale. The highest potential price, because you split the spread with the buyer instead of giving it all to a dealer. The cost is trust and logistics: a safe meeting place, a way to verify funds, and a buyer who can verify the metal. Best for those already in a local collector or investor network.
Refiner or smelter. For large bars or scrap, a refiner will assay and pay on metal content. Slowest channel, but it removes the question of whether your bar is recognized, the refiner melts it down.
The Buy-Sell Spread, in Plain Terms
The spot price is the benchmark, but you never trade at spot. You buy at spot plus a premium and sell at spot minus a discount, and the gap is your real cost of ownership. A one-ounce sovereign coin from a major mint typically carries a higher premium than a large bar, because coins are more recognizable and easier to resell in small units; the discount on the way out is smaller for the same reason. So buy the most recognizable, standard product you can afford, and hold it long enough that the spread is a rounding error against the move you are trying to capture. Gold rewards patience over frequent trading.
Common Mistakes That Cost Real Money
- Buying without checking purity and weight invites counterfeits and mispriced metal.
- Ignoring the buy-sell spread turns a good asset into a costly one for anyone who trades in and out.
- No records complicates taxes and resale, keep every receipt showing date, quantity, purity, and price.
- Storing without insurance leaves a total loss on the table.
- Confusing numismatic value with bullion value. A rare coin may carry a collector premium; a plain bar trades close to spot. These are separate markets with separate buyers, know which one you own before you sell.
Before you buy anything, call two local dealers and ask what they would pay for a one-ounce sovereign coin today, and ask what they would charge you to buy one back. The difference between those two numbers is your real round-trip cost, and it tells you more about your exit price than any article can.
Frequently Asked Questions
Is it worth it to own physical gold bullion?
It depends on your goals. Physical gold bullion works as a long-term store of value and inflation hedge, especially when you hold it for years rather than trade short-term. It carries no counterparty risk because you own the metal directly. However, you pay dealer premiums, storage costs, and capital gains taxes when you sell. For investors wanting 5-10% of their portfolio in a tangible asset that holds value during economic crisis, it can be worth it.
What are the primary tax implications of owning physical gold bullion?
The IRS treats physical gold as a collectible, taxed at a maximum rate of 28% on long-term capital gains, higher than the 20% rate for most other investments. You owe taxes when you sell, not when you buy. Dealers must report cash transactions over $10,000 on Form 8300. Some gold coins and bars also require Form 1099-B reporting when sold. Track your purchase price and sale price carefully to calculate your gain accurately.
How does physical gold differ from gold ETFs in terms of ownership?
When you buy a gold ETF, you own shares in a fund that holds gold, not the metal itself. You face counterparty risk if the fund or custodian fails. Physical gold bullion gives you direct ownership and physical possession. You can hold it, store it where you choose, and sell it to any dealer. The trade-off is storage logistics, insurance costs, and wider buy-sell spreads compared to ETF trading.
What are the downsides of buying physical gold bullion?
Physical gold has real drawbacks. Dealer markups and premiums raise your break-even price. Storage and insurance add ongoing costs. Selling takes longer than clicking a button in a brokerage account, and you may face wider spreads. The IRS taxes gold gains at 28%, higher than stocks. Gold pays no dividends or interest, so it produces no income while you hold it. These factors matter most for short-term holders.